Smoke Damage Without Flames: A Common but Confusing Scenario
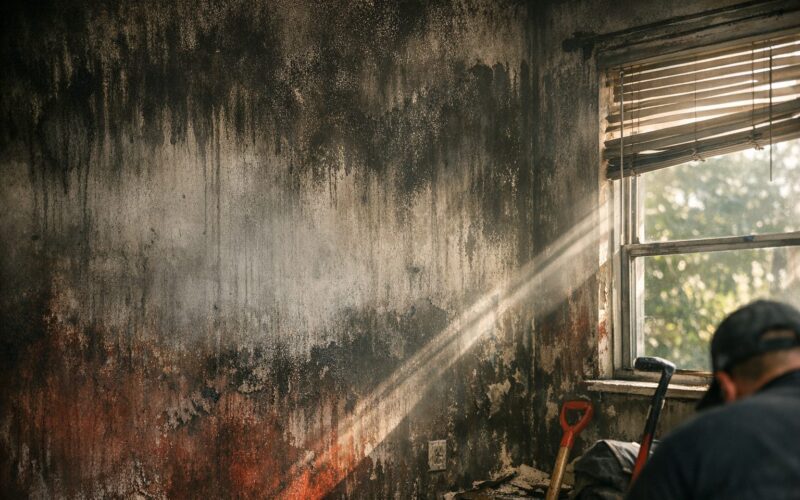
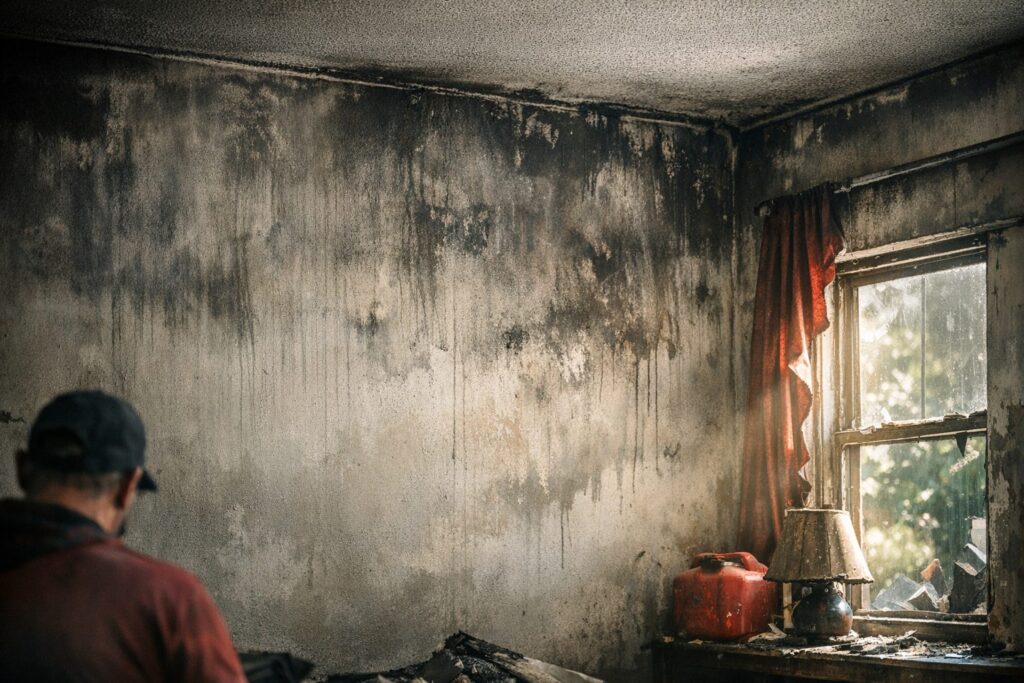
You come home to find your house filled with a strong, acrid smell. The walls have a hazy film. Your white curtains have turned gray. But there is no sign of fire — no charring, no flames, no burned materials. How did this happen, and will your insurance cover it?
Smoke damage without visible fire is more common than most homeowners realize. It can result from smoldering electrical components, HVAC malfunctions, a nearby wildfire or structure fire, or even a furnace puffback. The good news is that most standard homeowner’s insurance policies do cover this type of damage. The challenge is knowing how to document and file the claim properly to ensure fair compensation.
Common Causes of Smoke Damage Without Open Flames
Electrical Smoldering
Overheated wiring, a failing electrical connection, or a malfunctioning appliance can smolder inside a wall cavity or appliance housing without producing an open flame. The resulting smoke circulates through the home via the HVAC system, depositing soot and odor-causing residue on every surface. By the time the smell becomes noticeable, the contamination may be extensive.
HVAC Malfunctions
A heat exchanger failure, burned-out blower motor, or electrical short within the air handler can produce smoke that the system then distributes to every room through the ductwork. Because the HVAC system actively pushes the smoke throughout the house, contamination is typically uniform and widespread.
Furnace Puffback
While less common in Florida than in northern states, homes with oil or gas furnaces can experience puffbacks — small explosions inside the combustion chamber that blow soot and smoke throughout the duct system and into every room. A single puffback event can coat an entire home in fine black soot.
Neighbor’s Fire or Nearby Wildfire
Smoke from a fire at a neighboring property or from a Florida wildfire can infiltrate your home through open windows, attic vents, and air infiltration points. Even with all windows closed, significant smoke events can force smoke into the home through normal air leakage paths.
Cooking Incidents
A forgotten pot or pan that smokes heavily without catching fire can produce enough residue to damage surfaces, fabrics, and air quality throughout the kitchen and adjacent rooms.
Does Standard Homeowner’s Insurance Cover Smoke-Only Damage?
Yes, in most cases. Standard homeowner’s insurance policies — including HO-3 policies common in Florida — cover smoke damage as a named peril. This coverage applies regardless of whether there was an open flame, because the policy language typically covers damage caused by “fire or smoke” as a single peril.
What Is Typically Covered
- Professional cleaning of all smoke-affected surfaces — walls, ceilings, floors, fixtures
- HVAC system cleaning if the ductwork distributed smoke throughout the home
- Professional odor removal including thermal fogging, ozone, or hydroxyl treatment
- Repainting after smoke-sealing primer application
- Carpet and soft goods cleaning or replacement if they cannot be restored
- Contents cleaning or replacement for personal belongings damaged by smoke
- Additional Living Expenses if smoke damage makes the home uninhabitable during restoration
Potential Exceptions and Limitations
While smoke damage is generally covered, there are scenarios where coverage may be limited or denied:
- Gradual damage: If the smoke damage resulted from a long-term condition (such as a fireplace that has been leaking smoke into the home for months) rather than a sudden event, the insurer may argue it is maintenance-related
- Negligence: If the damage resulted from clear negligence — deliberately burning materials indoors, for example — coverage may be denied
- Wildfire smoke exclusions: Some Florida policies have specific exclusions or sublimits for wildfire-related damage, particularly in brush fire-prone areas
- Intentional acts: Deliberate creation of smoke damage is never covered
How to File a Smoke Damage Claim Successfully
Smoke-only claims can be more challenging to get approved at full value than fire claims because the damage is less visually dramatic. Insurance adjusters may underestimate the scope of contamination when they cannot see charred materials or structural damage. To protect your claim:
1. Document Thoroughly
- Photograph every room, including surfaces that appear clean — professional testing may reveal contamination that is not visible to the eye
- Record video walking through the home, narrating the smoke odor and visible residue
- Photograph soot on HVAC registers, inside cabinets, on light-colored fabrics, and on any surface where contamination is visible
- If the source was an appliance or electrical issue, preserve the failed component and photograph it in place before removal
2. Do Not Clean Before the Adjuster Visits
It is tempting to start cleaning immediately, but doing so removes the evidence your adjuster needs to assess the claim. Take photographs and video first, then wait for the adjuster’s inspection before beginning cleanup. If you must take immediate action to prevent further damage (your duty to mitigate), document everything before and during your efforts.
3. Get a Professional Assessment
A professional restoration company’s assessment carries significant weight with insurance adjusters. At WrightWay Emergency Services, we provide detailed Xactimate estimates that document every aspect of the smoke damage — including contamination in areas the adjuster may not inspect, such as inside HVAC ducts, wall cavities, and attic spaces.
4. Request Air Quality Testing
If the insurance adjuster questions the extent of the damage, independent air quality testing provides objective evidence of contamination. Particulate counts and VOC measurements document conditions that photographs alone cannot convey.
Common Adjuster Pushback and How to Respond
WrightWay documents every loss to insurance standards, photos, moisture logs, and itemized scopes your adjuster can approve without back-and-forth.
Insurance adjusters for smoke-only claims sometimes minimize the scope. Common pushback includes:
- “You just need to air out the house.” — Ventilation does not remove smoke particles embedded in porous materials. Professional cleaning is required.
- “We’ll cover cleaning but not repainting.” — If smoke-sealing primer is required to prevent odor bleed-through (which it almost always is), repainting is a necessary restoration step, not a cosmetic upgrade.
- “The HVAC doesn’t need professional cleaning.” — If the system was running during the smoke event, the ductwork is contaminated and will recirculate particulate matter until professionally cleaned.
- “Your contents just need to be wiped down.” — Porous items like upholstery, clothing, and books absorb smoke at a molecular level. Surface wiping is insufficient for meaningful decontamination.
Having a professional restoration company’s documentation and scope of work gives you the evidence needed to support your position on each of these points.
The Restoration Process for Smoke-Only Damage
Professional smoke damage restoration follows a proven sequence:
- Assessment and documentation of all affected areas
- Contents evaluation, pack-out, and cleaning at a professional facility
- Surface cleaning of walls, ceilings, and hard surfaces
- HVAC system cleaning
- Professional odor removal using industrial-grade equipment
- Smoke-sealing primer on all affected surfaces
- Repainting throughout affected areas
- Contents return once the home is restored
Smoke Damage Without Fire? Call WrightWay
If your home has sustained smoke damage — whether from a smoldering electrical issue, HVAC malfunction, nearby fire, or any other source — WrightWay Emergency Services can help. We provide comprehensive smoke damage restoration and expert insurance claims assistance throughout Sarasota, Fort Myers, Naples, and all of Southwest Florida.
Call us at (941) 379-8669 for a professional assessment. We document the full scope of damage, produce insurance-ready estimates, and restore your home to pre-loss condition.
WrightWay handles every restoration job from emergency response through licensed reconstruction.
One IICRC-certified team, one project manager, one phone call. Available 24/7 across Sarasota, Manatee, Charlotte, Lee, and Collier counties.