The Contents Inventory: The Most Overwhelming Part of a Fire Claim
After a fire, your insurance company will ask you to produce a complete inventory of every personal belonging that was damaged or destroyed. Every dish in the kitchen, every shirt in the closet, every tool in the garage, every toy in the children’s rooms. The inventory must include descriptions, estimated values, and ideally proof of purchase or ownership.
For most homeowners, this is the most overwhelming and emotionally draining part of the fire recovery process. You are already dealing with the trauma of a fire, potential displacement from your home, and the stress of coordinating restoration — and now you must recall and list potentially thousands of individual items from memory. Yet the thoroughness and accuracy of this inventory directly determines how much your insurance company pays for your personal property claim.
Why the Contents Inventory Matters So Much
Your homeowner’s insurance personal property coverage pays only for items you claim. If you forget to list an item, you will not be reimbursed for it. If you undervalue an item, you will receive less than its replacement cost. If you cannot provide adequate documentation, the adjuster may reduce or deny individual items.
The stakes are significant. In a moderate house fire, the contents claim can easily reach $50,000 to $150,000 or more. In a total loss, contents claims frequently exceed the structural damage. Every item you overlook is money you leave on the table.
Start With What You Can See
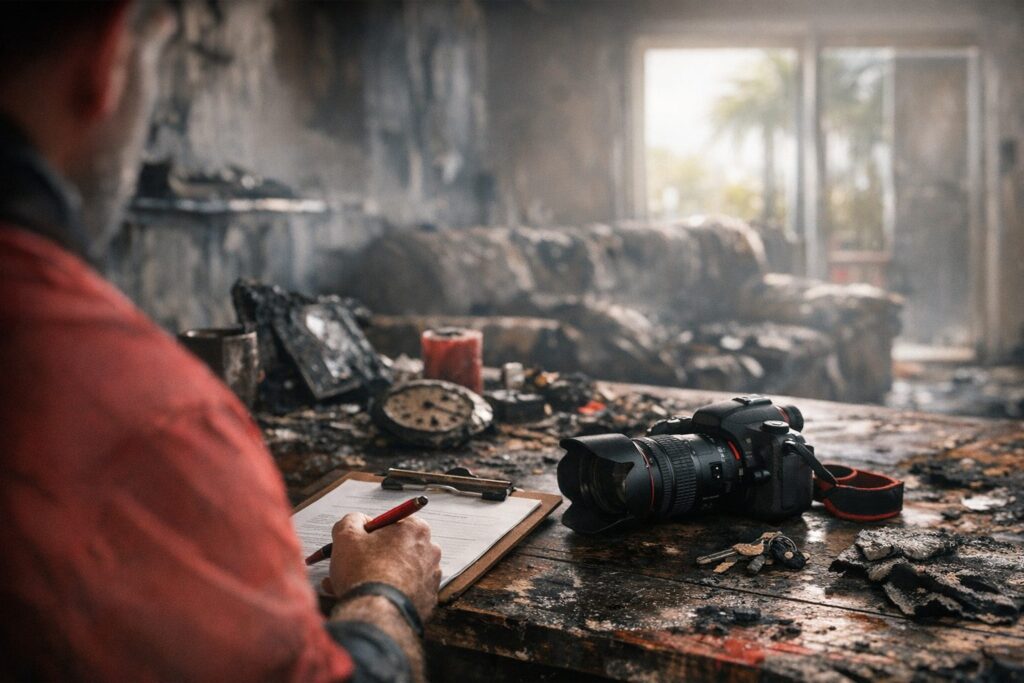
Begin your inventory with the damaged items that are still physically present. Walk through the home room by room (once it is safe to enter) and document everything:
How to Document Each Room
- Photograph the entire room from multiple angles, showing the overall condition
- Photograph each damaged item individually — close enough to see the damage and any identifying information (brand, model, serial number)
- Open every drawer, cabinet, and closet and photograph the contents
- Check under furniture, behind doors, and in storage areas
- Record video narrating what each item is, its approximate age, and where it was purchased
Information to Record for Each Item
For each item on your inventory, provide as much of the following information as possible:
- Item description: Be specific — not “TV” but “Samsung 65-inch QLED Smart TV, Model QN65Q80A”
- Brand and model: When identifiable
- Purchase date: Approximate is acceptable
- Purchase price: Original cost when purchased
- Current replacement cost: What it would cost to buy the same or equivalent item today
- Condition before the fire: New, good, fair, or poor
- Condition after the fire: Damaged, destroyed, or smoke-contaminated
The Room-by-Room Approach
Organize your inventory by room. This systematic approach ensures you do not miss entire categories of belongings. For each room, think through these categories:
Kitchen
- Small appliances (toaster, coffee maker, blender, mixer, food processor, instant pot)
- Large appliances (if owned, not builder-installed)
- Cookware (pots, pans, baking sheets, casserole dishes)
- Dinnerware (plates, bowls, mugs, glasses)
- Flatware and utensils
- Knives and cutting boards
- Food storage containers
- Spice rack and contents
- Pantry contents (food items have replacement value)
- Cleaning supplies
Living and Family Rooms
- Furniture (sofas, chairs, tables, entertainment centers, bookshelves)
- Electronics (TVs, sound systems, gaming consoles, streaming devices)
- Decorative items (artwork, frames, vases, sculptures, candles)
- Books, DVDs, and media
- Rugs and window treatments
- Lamps and lighting
Bedrooms
- Bed frames and mattresses
- Bedding (sheets, comforters, pillows, blankets — each set counts separately)
- Dressers, nightstands, and wardrobes
- Clothing (itemize by type — shirts, pants, dresses, shoes, coats)
- Jewelry and watches
- Personal electronics (phones, tablets, laptops, chargers)
Bathrooms
- Towels and bath linens
- Personal care products and cosmetics
- Hair dryers, straighteners, and grooming tools
- Medications (both prescription and over-the-counter)
Garage and Outdoor
- Power tools and hand tools
- Lawn equipment (mower, trimmer, blower)
- Sporting goods (bicycles, golf clubs, fishing gear)
- Holiday decorations
- Automotive supplies
- Patio furniture and grill
Finding Proof of Ownership and Value
Your insurance company will accept various forms of documentation to verify your claimed items:
- Receipts and credit card statements: Check your email for digital receipts. Log into your Amazon, Walmart, Target, and other retail accounts for purchase history. Request credit card statements going back several years.
- Photos and videos: Review your phone’s photo library, social media posts, and cloud storage. Background photos often capture furnishings and belongings you would not otherwise document.
- Product registration: If you registered appliances or electronics, those records prove ownership and purchase date.
- Home inventory apps: If you used a home inventory app or created a spreadsheet before the fire, this is invaluable.
- Appraisals: Professional appraisals for jewelry, art, antiques, and other valuables.
- Owner’s manuals and warranty cards: If these survived (or if you have digital copies), they document specific items.
Replacement Cost vs. Actual Cash Value
Need restoration help in Southwest Florida right now? WrightWay dispatches in 60 to 90 minutes from three Florida offices, and we answer with a live human.
Understanding your policy’s valuation method is critical:
- Replacement Cost Value (RCV): Pays the current cost to replace each item with a new item of like kind and quality. This is the more favorable valuation for homeowners. Most RCV policies pay the depreciated value upfront and the remainder after you actually replace the item.
- Actual Cash Value (ACV): Pays the replacement cost minus depreciation based on the item’s age and condition. A five-year-old television that cost $1,200 new might have an ACV of only $300 to $500.
If you have an RCV policy, it is worth replacing items even when the upfront ACV payment seems low, because you can claim the depreciation holdback once replacement is completed.
Common Mistakes That Reduce Your Settlement
- Rushing the inventory: Take your time. Most insurance companies give you up to a year (sometimes longer) to submit your complete contents inventory. A thorough list submitted over several weeks will yield a higher settlement than a rushed one submitted in days.
- Using vague descriptions: “Clothing — $2,000” will be questioned. “12 men’s dress shirts, Brooks Brothers, $85 each” is specific and defensible.
- Forgetting categories: Items in the attic, holiday decorations, garage contents, and pantry food are commonly forgotten.
- Not claiming smoke-damaged items: Items that were not burned but smell like smoke or have soot contamination are damaged. If professional contents cleaning cannot restore them, they should be on your inventory as losses.
- Accepting the adjuster’s first offer: Initial settlements are often negotiable, especially when you provide additional documentation.
How a Restoration Company Helps With Contents Documentation
WrightWay Emergency Services supports your contents claim through our contents cleaning and restoration services:
- Professional contents pack-out with detailed, item-by-item inventory
- Photographic documentation of every item during pack-out
- Professional cleaning and deodorization of salvageable items
- Written assessment of items that cannot be restored to pre-loss condition
- Coordination with your insurance adjuster on contents valuation
Protect Your Claim — Call WrightWay
If a fire has damaged your home and belongings, WrightWay Emergency Services provides complete fire damage restoration and professional contents services throughout Sarasota, Fort Myers, Naples, and all of Southwest Florida. We help you navigate the insurance claims process from first call through final settlement.
Call us at (941) 379-8669 — we respond 24/7. Let our experience work for you during the most challenging time.
WrightWay handles every restoration job from emergency response through licensed reconstruction.
One IICRC-certified team, one project manager, one phone call. Available 24/7 across Sarasota, Manatee, Charlotte, Lee, and Collier counties.