Filing a Property Damage Claim in Florida: What You Need to Know
When a burst pipe floods your kitchen, a storm tears shingles off your roof, or a fire damages your living room, the insurance claim you file determines whether your home gets properly restored or you end up paying thousands out of pocket. Florida has specific deadlines, requirements, and processes that differ from other states, and understanding them before disaster strikes gives you a significant advantage.
This guide from WrightWay Emergency Services walks you through every step of filing a property damage claim in Florida, from the moment damage occurs through final payment. We have helped thousands of Southwest Florida homeowners navigate this process, and we know exactly what separates successful claims from underpaid or denied ones.
Step 1: Ensure Safety and Prevent Further Damage
Before you think about insurance paperwork, make sure everyone in your household is safe. Once the immediate danger has passed, Florida law requires you to take reasonable steps to prevent further damage to your property. This is called your duty to mitigate, and failing to do so can give your insurer grounds to deny part of your claim.
Reasonable Mitigation Steps
- Water damage: Shut off the water source, move furniture away from standing water, and begin removing excess water if you can do so safely
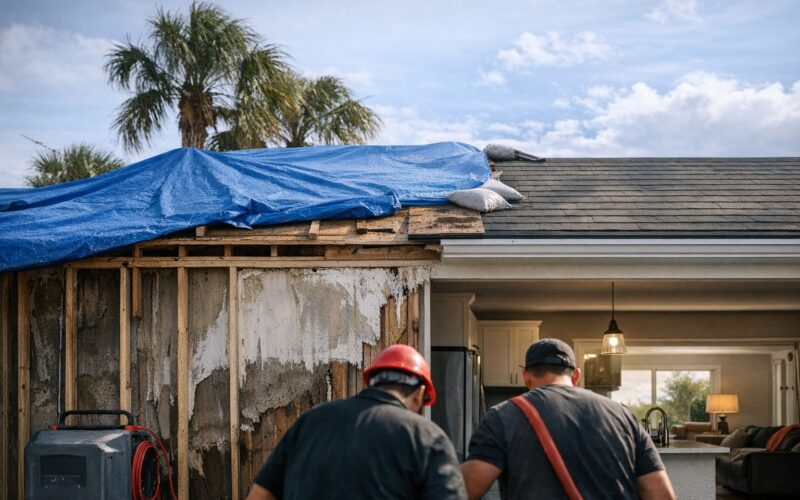
- Roof damage: Place tarps over exposed areas or have a professional tarp the roof
- Fire damage: Board up broken windows and secure the property against unauthorized entry
- Broken pipes or plumbing: Shut off the main water supply valve
Keep all receipts for emergency supplies and temporary repairs. These costs are typically reimbursable under your policy. If damage is extensive, call a professional restoration company like WrightWay Emergency Services immediately. We respond 24/7 and can begin emergency mitigation within 60 to 90 minutes across Sarasota, Fort Myers, Naples, and surrounding areas.
Step 2: Document Everything Before Cleanup Begins
Documentation is the foundation of a successful insurance claim. Before you move anything, clean anything, or throw anything away, grab your smartphone and create a thorough record of the damage.
Photo and Video Documentation Checklist
- Wide-angle shots of every affected room showing the full scope of damage
- Close-up photos of specific damaged items, materials, and structural elements
- Video walkthroughs narrating what you see and where the damage extends
- Photos of the damage source (burst pipe, entry point of water, fire origin if visible)
- Images of your home’s exterior if storm-related damage is involved
- Photographs of serial numbers, model numbers, and brand labels on damaged appliances and electronics
Time-stamp your documentation. Most smartphones embed date and time in photo metadata, but you can also include a newspaper or display a clock in some images as additional verification.
Step 3: Contact Your Insurance Company Promptly
Important: Before calling your insurance company, contact a professional restoration company like WrightWay Emergency Services. Your restoration company begins professional documentation and emergency mitigation immediately — fulfilling your policy’s duty to mitigate and providing the thorough evidence (photos, moisture readings, Xactimate estimates) that strengthens your claim. Having this professional documentation in hand when you call your insurer puts you in a stronger position from the start.
Florida law does not specify an exact deadline for reporting property damage to your insurer, but most policies include a prompt notice requirement. As a best practice, contact your insurance company within 24 to 48 hours of discovering the damage. For hurricane or storm damage, Florida Statute 627.70132 requires you to file your claim within two years of the date of loss, but waiting even a few weeks can raise red flags.
Information to Have Ready When You Call
- Your policy number
- Date and time the damage occurred or was discovered
- A brief description of what happened and what is damaged
- Whether emergency repairs have been made
- Contact information for where you can be reached
When you report the claim, your insurer will assign a claim number. Write this number down immediately and reference it in every future communication. Ask for the name and direct contact information of the adjuster assigned to your claim.
Step 4: Review Your Policy Before the Adjuster Arrives
Between filing your claim and the adjuster’s visit, read your policy carefully. Understanding your coverage before negotiations begin puts you in a much stronger position. Pay attention to:
| Policy Element | What to Look For |
|---|---|
| Dwelling Coverage (Coverage A) | Maximum amount for structural repairs |
| Personal Property (Coverage C) | Limits for contents; actual cash value vs. replacement cost |
| Loss of Use (Coverage D) | Additional living expenses if your home is uninhabitable |
| Deductible | Dollar amount or percentage you pay before coverage kicks in |
| Hurricane Deductible | Separate, often higher deductible for named storms |
| Exclusions | What is specifically not covered (flood, mold limits, earth movement) |
| Ordinance or Law | Whether code-upgrade costs are covered during reconstruction |
Step 5: Prepare for the Adjuster’s Inspection
Your insurance company will send a field adjuster to inspect the damage, typically within a few days to two weeks of your filing. In Florida, after a hurricane or widespread event, this timeline may stretch longer due to volume. Here is how to prepare:
- Be present during the inspection and walk the adjuster through every area of damage
- Share your documentation including all photos, videos, and receipts for emergency repairs
- Point out hidden damage that may not be immediately visible, such as water behind walls or under flooring
- Provide a personal property inventory listing damaged items with their approximate age, purchase price, and replacement cost
- Do not agree to a scope of damage on the spot if you feel the adjuster is overlooking areas
If you have already engaged a restoration company, ask them to be present during the inspection or provide their assessment. At WrightWay Emergency Services, we routinely meet with adjusters on-site and share our moisture readings, damage assessments, and scope documentation to ensure nothing is missed.
Step 6: Get a Professional Restoration Estimate
WrightWay documents every loss to insurance standards, photos, moisture logs, and itemized scopes your adjuster can approve without back-and-forth.
Do not rely solely on your insurance company’s estimate. Obtain an independent estimate from a licensed restoration contractor who uses Xactimate, the same estimating software your insurer uses. This creates an apples-to-apples comparison that makes disputes easier to resolve.
A thorough restoration estimate should include:
- Emergency mitigation (water extraction, board-up, tarping)
- Structural drying with equipment inventory and duration
- Demolition of damaged materials (drywall, flooring, insulation)
- Mold remediation if applicable
- Reconstruction to pre-loss condition including all materials and labor
- Code-upgrade costs if your municipality requires them
Step 7: Review the Adjuster’s Report and Settlement Offer
After the inspection, your insurer will issue a written estimate and settlement offer. Review it line by line and compare it against your contractor’s estimate. Common areas where insurance estimates fall short include:
- Underestimating the affected area (square footage of damaged drywall, flooring, etc.)
- Omitting overhead and profit for the contractor
- Using actual cash value instead of replacement cost for contents
- Ignoring code-upgrade requirements
- Excluding related damage (mold that developed from water damage, for example)
If the settlement offer is lower than your contractor’s estimate, you have the right to negotiate. Provide your contractor’s Xactimate estimate, supporting photos, and any other documentation that supports your position.
Step 8: Negotiate or Dispute if Necessary
If negotiations with the adjuster stall, you have several options under Florida law:
- Request a re-inspection: Ask for a senior adjuster or a different adjuster to review the claim
- File a complaint with the Florida Department of Financial Services: This puts regulatory pressure on the insurer
- Invoke appraisal: Most policies include an appraisal clause that allows each party to hire an appraiser, with an umpire resolving disputes
- Consult a public adjuster or attorney: For significant underpayments, professional representation may be worthwhile
For more on these dispute resolution options, see our guide on insurance claims assistance.
Step 9: Begin Repairs and Track All Expenses
Once you have reached a settlement, begin restoration work with your chosen contractor. Keep meticulous records of all expenses, change orders, and communications. If additional damage is discovered during repairs (which is common with water and fire damage), notify your insurance company immediately and document the newly discovered damage before proceeding.
Step 10: Collect Any Remaining Payments
Many replacement cost policies pay in two stages. The first payment covers the actual cash value (replacement cost minus depreciation). The second payment, called recoverable depreciation, is released after you complete repairs and submit proof that the work has been done. Make sure you understand this process and submit your completion documentation promptly.
Need Help With Your Florida Property Damage Claim?
WrightWay Emergency Services has guided thousands of Florida homeowners through the claims process. From emergency mitigation through complete reconstruction, we handle the restoration while helping you maximize your insurance recovery. We write Xactimate estimates, meet with adjusters, and document every detail so nothing is left on the table.
Call us at (941) 379-8669 any time, day or night. We are here to help you recover.
WrightWay handles every restoration job from emergency response through licensed reconstruction.
One IICRC-certified team, one project manager, one phone call. Available 24/7 across Sarasota, Manatee, Charlotte, Lee, and Collier counties.