Understanding Collier County Flood Zones: A Guide for Homeowners and Property Managers
Collier County, Florida, is defined by its diverse and flood-vulnerable geography – the Gulf coastline, the Ten Thousand Islands, tidal estuaries, and low-lying eastern flatlands. This unique landscape makes the area especially susceptible to flooding during hurricane season and periods of heavy rainfall. For residents and property managers in Naples, Marco Island, Bonita Springs, Estero, Immokalee, and surrounding communities, understanding FEMA flood zone designations is essential for protecting property, managing insurance costs, and responding quickly when floodwaters arrive.
FEMA Flood Zone Designations in Collier County
FEMA assigns flood zone designations to every parcel in Collier County through its Flood Insurance Rate Maps (FIRMs). These designations determine insurance requirements, building codes, and permitting standards. Understanding where your property falls on these maps can affect your mortgage, your annual insurance premium, and your recovery options after a storm.
Zone VE – Coastal Velocity Hazard
Zone VE represents the highest-risk areas in Collier County. These are coastal high-hazard zones where storm surge combines with breaking wave action – a force far more destructive than standing water alone. In Collier County, VE designations appear along the beachfront areas of Naples and portions of Marco Island’s Gulf-facing shoreline. Properties in Zone VE must comply with the most stringent building standards: open foundations on pilings, breakaway walls, and no obstruction below the base flood elevation. If you own a beachfront property in Naples or Marco Island, check your current FIRM panel to confirm whether you fall in VE or AE, since the 2024 map update shifted some boundaries.
Zone AE – High-Risk Inland and Coastal Flooding
Zone AE is the most common high-risk flood designation in Collier County and covers the largest geographic footprint of the Special Flood Hazard Area (SFHA). AE zones include the Naples waterfront communities, the Gordon River corridor, communities along US-41, tidal areas of Marco Island, and many low-lying neighborhoods throughout the county. In Zone AE, properties with federally backed mortgages are required to carry flood insurance, and all new construction must meet base flood elevation standards. On Marco Island specifically, AE is the dominant flood zone designation – VE applies to the direct beachfront, while most of the island’s interior and bay-side areas fall within AE.
Zone X (Shaded) – Moderate Risk
Zone X shaded, also labeled Zone B in older maps, indicates a moderate flood hazard – specifically a 0.2% annual chance of flooding, sometimes described as the “500-year flood” level. Flood insurance is not federally mandated for properties in this zone, but it is still available through the National Flood Insurance Program (NFIP) and private carriers, often at lower premiums than high-risk zones. Some neighborhoods in Bonita Springs and eastern Naples fall in shaded X zones.
Zone X (Unshaded) – Minimal Risk
Zone X unshaded represents areas of minimal flood risk – outside the 500-year floodplain. Immokalee and the drier eastern portions of Golden Gate Estates carry this designation in many areas. However, “minimal risk” does not mean zero risk. Heavy rainfall events, overwhelmed stormwater systems, and localized drainage failures can still produce flooding in unshaded X zones. FEMA data shows that about 25% of all flood insurance claims come from outside the high-risk flood zones.
The 2024 Collier County FIRM Update: What Changed
Collier County’s updated Flood Insurance Rate Maps became effective February 8, 2024 – the first comprehensive FIRM update for the county since 2012. The revised maps incorporate more than a decade of updated hydrology, topographic LiDAR data, and changes in land use and drainage patterns. This is not specifically a post-Hurricane Ian revision – Ian struck just weeks before the previously scheduled November 2022 effective date, and that update went through as planned. The February 2024 maps reflect cumulative changes over more than a decade of development, erosion, and shifting water flow patterns throughout the county.
What this means for property owners: your flood zone designation may have changed from what your lender or insurance agent last documented. A property that was in Zone X in 2012 may now fall in Zone AE, triggering a mandatory flood insurance requirement. Conversely, some properties may have moved into lower-risk zones, potentially reducing premiums. Collier County’s floodplain management office can be reached at (239) 252-2942 or [email protected] with questions about how the 2024 maps affect your specific parcel.
Beyond the 2024 adopted maps, FEMA presented preliminary updated FIRMs at public open houses in June 2025 – a further round of revisions based on additional modeling. Property owners should monitor FEMA’s Map Service Center for any new preliminary maps affecting their parcels.
How to Look Up Your Collier County Flood Zone
The FEMA Flood Map Service Center (msc.fema.gov) is the official public source for flood hazard information. Here is how to use it:
- Go to msc.fema.gov and enter your full property address in the search bar.
- Select your address from the results to open the flood map viewer.
- In areas with modernized data (which includes all of Collier County), you will see an “Interactive Map” option that opens the National Flood Hazard Layer – this shows your flood zone, base flood elevation, and panel boundaries without downloading any files.
- Note your flood zone designation and the FIRM panel number for reference when speaking with your insurer or mortgage lender.
If you want a second-opinion risk view that goes beyond FEMA’s regulatory maps, the First Street Foundation’s Flood Factor tool provides property-level flood risk scores based on climate-adjusted modeling that factors in events FEMA maps do not.
Marco Island: Barrier Island Flood Risk
Marco Island is a barrier island fully within FEMA-designated flood zones – every parcel on the island sits inside either an AE, VE, or X zone. The current FIRM for Marco Island carries the February 8, 2024 effective date. The beachfront and Gulf-facing perimeter of the island carries VE designations, where wave action is the primary hazard driver. The majority of Marco Island’s developed area – interior streets, the bay side, and most residential neighborhoods – falls in Zone AE, subject to base flood elevation requirements and mandatory flood insurance for federally mortgaged properties.
Marco Island is also part of Collier County’s Evacuation Zone A, the highest-priority zone for mandatory evacuation orders during major hurricanes. Property owners on Marco Island should maintain current elevation certificates and review their flood zone status against the 2024 FIRM to ensure their insurance premiums reflect the correct designation.
Naples Waterfront Communities
The waterfront neighborhoods of Naples sit in some of the most flood-exposed real estate in Florida. Communities including Royal Harbor, Port Royal, the Moorings, Park Shore, and Pelican Bay carry high-risk AE and in some locations VE designations. Homeowners in these areas face mandatory flood insurance requirements on federally backed mortgages and must comply with Collier County’s floodplain management regulations for any construction, renovation, or addition.
Naples also saw significant flood damage from Hurricane Ian in 2022, even though Ian’s eye made landfall further north near Fort Myers. Storm surge of several feet was recorded in parts of Naples, underscoring why the high-risk zone designations in these communities are not theoretical – they reflect genuine recurring exposure.
Golden Gate Estates: Inland Flooding Risks
Golden Gate Estates is largely designated Zone X – either shaded or unshaded – yet flooding is a real and recurring problem here. The reason is simple: the Estates’ flatlands have limited natural drainage, and heavy rainfall or canal overflow can inundate low-lying lots quickly. Unlike Zone AE flooding that comes primarily from storm surge, Golden Gate Estates flooding typically comes from sustained rainfall that exceeds the drainage capacity of the canal system. Homeowners here should review the Collier County stormwater drainage maps alongside the FEMA flood maps to get a complete picture of their risk.
Bonita Springs Flood Risk
Bonita Springs, at the northern edge of Collier County, has its own documented history of serious flood events. The Imperial River corridor and downtown Bonita Springs have flooded repeatedly during major storms. Much of Bonita Springs along the river and its tributaries falls in Zone AE. Hurricane Ian produced catastrophic flooding in Bonita Springs in September 2022, with some areas experiencing the worst flooding in decades. Property owners in Bonita Springs should verify their current flood zone status using the 2024 FIRM, as some areas may have been reclassified.
Mandatory Flood Insurance in Collier County
Flood insurance is mandatory for properties in Zone AE, Zone VE, and other Special Flood Hazard Areas when the property carries a federally backed mortgage (FHA, VA, conventional loans sold to Fannie Mae or Freddie Mac). The two primary sources for flood coverage are:
- National Flood Insurance Program (NFIP): The federal program administered through FEMA and sold by participating private insurers. NFIP policies cover up to $250,000 for the building structure and up to $100,000 for contents. Learn more at FloodSmart.gov, the official NFIP consumer resource.
- Private flood insurance: Private carriers may offer higher coverage limits, broader terms, and in some cases lower premiums than the NFIP – especially for higher-value homes. Coverage and pricing vary significantly by carrier and property characteristics.
Even for properties outside high-risk zones, flood insurance is worth serious consideration. A standard homeowners policy does not cover flood damage, and even a few inches of water in a home can cause tens of thousands of dollars in damage.
FEMA Risk Rating 2.0 and Your Insurance Premium
WrightWay documents every loss to insurance standards, photos, moisture logs, and itemized scopes your adjuster can approve without back-and-forth.
FEMA implemented Risk Rating 2.0 in 2021 and 2022, replacing a decades-old pricing methodology with one that calculates premiums based on individual property characteristics: distance to water, foundation type, first-floor elevation relative to base flood elevation, and the cost to rebuild. For many Collier County coastal properties, Risk Rating 2.0 has meant higher premiums – often significantly higher – because the old system underpriced risk for high-value homes near water. Some inland properties in lower-risk zones saw decreases. If your flood insurance premium has increased sharply in recent years, it is almost certainly Risk Rating 2.0 at work, not a change in your flood zone designation. You can shop private carriers as an alternative, and an elevation certificate may help document that your property’s actual risk is lower than FEMA’s default assumptions.
Letters of Map Amendment (LOMA): Challenging Your Flood Zone
If your property has been designated in a high-risk flood zone but the actual ground elevation of your lot and structure is at or above the Base Flood Elevation (BFE), you may be eligible for a Letter of Map Amendment (LOMA) from FEMA. A LOMA can remove your property from the SFHA, potentially eliminating a mandatory flood insurance requirement and reducing your premiums.
Key facts about the LOMA process:
- Cost: Submitting a LOMA to FEMA is free. There is no federal application fee.
- Documentation required: You will need an elevation certificate prepared by a licensed Florida land surveyor or professional engineer, showing that the lowest adjacent grade of the structure (and the lowest point on the lot, for full-lot removal) is at or above the BFE.
- How to apply: Submit through FEMA’s online LOMC tool at hazards.fema.gov/femaportal/onlinelomc, by mail to FEMA, or through the eLOMA system for straightforward cases.
- Timeline: FEMA typically issues its determination within 60 days of receiving a complete application.
- Result: A successful LOMA results in an official FEMA letter reclassifying your property. You can present this to your lender to remove the mandatory flood insurance requirement, though you may still choose to carry coverage voluntarily.
The cost of hiring a licensed surveyor for the elevation certificate (typically $300 to $600 in SW Florida) is often recovered within the first year of reduced insurance premiums. If you believe your property is higher than its current flood zone suggests, consult a licensed Florida surveyor about whether a LOMA is appropriate.
Collier County’s Substantial Improvement (50%) Rule
Collier County enforces FEMA’s Substantial Improvement rule: if the cost to repair or renovate a building in a Special Flood Hazard Area exceeds 50% of the structure’s pre-damage or pre-improvement market value, the entire structure must be brought into compliance with current floodplain management standards. In practice, this often means elevating the structure to or above the BFE, which can be costly. This rule applies to flood damage repairs, fire damage repairs, and voluntary renovations – not just flood events. Before starting any major repair project on a property in a Collier County flood zone, verify the project cost against this threshold with the county’s building department.
What to Do If Your Collier County Home Floods
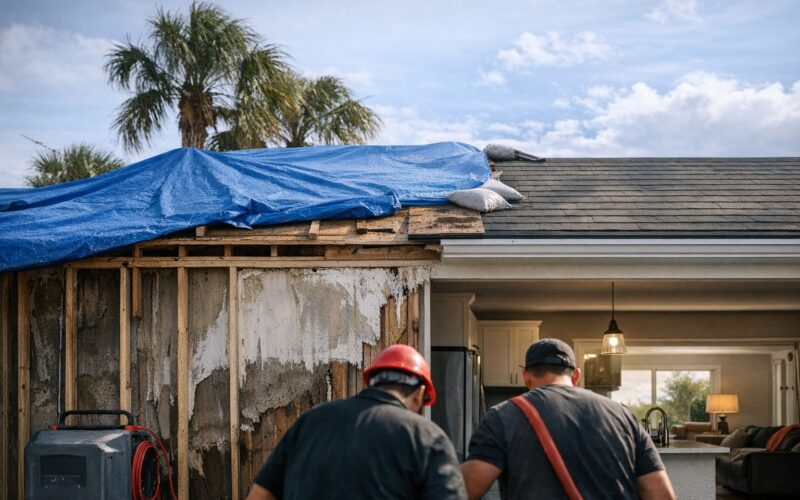
When flooding occurs, the window for effective action is short. Standing water accelerates mold growth – visible mold colonies can begin developing within 24 to 48 hours under Florida’s humidity and heat conditions. Here is the immediate priority sequence:
- Safety first: Do not enter a flooded structure until utilities have been shut off and the building is confirmed structurally sound. Contact your utility provider if you are unsure about power.
- Document everything before cleanup begins: Photograph and video all damage from multiple angles. This documentation is essential for your insurance claim.
- Contact a licensed restoration contractor: WrightWay Emergency Services (CBC1253650, IICRC certified) provides 24/7 emergency water extraction, structural drying, and mold remediation across SW Florida. Call (941) 379-8669 any time.
- Notify your insurance carrier: File your claim promptly. Your insurer may send an adjuster; having a restoration contractor on-site to document scope simultaneously protects your interests.
- Obtain permits: Major flood repairs in Collier County require permits. Your restoration contractor should coordinate with the county building department, particularly given the 50% rule discussed above.
Frequently Asked Questions
What is the highest risk flood zone in Collier County?
Zone VE is the highest-risk flood zone designation, covering the coastal beachfront areas of Naples and the Gulf-facing perimeter of Marco Island. VE zones are subject to both storm surge inundation and wave action, which is why building standards here are the most stringent – open piling foundations, breakaway walls, and no enclosed areas below the BFE are all required. Learn more about FEMA flood zone definitions.
How can I find out my property’s flood zone?
Visit msc.fema.gov and enter your property address. The interactive map tool will show your current flood zone designation based on the February 2024 Collier County FIRM. For questions specific to Collier County, you can also call the county’s floodplain management line at (239) 252-2942.
Is flood insurance mandatory in Collier County?
Flood insurance is mandatory for properties in high-risk zones (AE, VE, and other Special Flood Hazard Areas) when the property carries a federally backed mortgage. It is strongly recommended for all properties in SW Florida, including those in moderate-risk zones – standard homeowners policies do not cover flood damage. Visit FloodSmart.gov to learn more about NFIP coverage options.
What should I do if my home floods?
Act quickly. Document all damage with photos and video before touching anything, contact WrightWay Emergency Services at (941) 379-8669 for 24/7 water extraction and drying, and notify your flood insurance carrier to begin the claims process. Mold can begin growing within 24 to 48 hours in Florida’s climate, so professional drying is time-sensitive.
How does the 50% rule affect my property?
If repair costs exceed 50% of your structure’s pre-damage market value and your property is in a Special Flood Hazard Area, Collier County requires the entire structure to be brought into compliance with current floodplain regulations – which typically means elevating to or above base flood elevation. This rule applies to cumulative improvements over a rolling period as well, not just a single event. Consult Collier County’s building department before starting major repairs on any flood-zone property.
Is a Letter of Map Amendment (LOMA) free?
Yes. Submitting a LOMA application to FEMA is free. You will need to pay a licensed surveyor to prepare an elevation certificate (typically $300 to $600 in SW Florida), but FEMA charges no application fee. If approved, your LOMA can eliminate mandatory flood insurance requirements and significantly reduce your annual costs. Start the process at FEMA’s Change Your Flood Zone Designation page.
For 24/7 emergency water extraction and flood restoration across Collier County and SW Florida, call WrightWay Emergency Services at (941) 379-8669. We are IICRC certified, licensed contractor CBC1253650, and serve Naples, Marco Island, Bonita Springs, Estero, and the surrounding region.
WrightWay handles every restoration job from emergency response through licensed reconstruction.
One IICRC-certified team, one project manager, one phone call. Available 24/7 across Sarasota, Manatee, Charlotte, Lee, and Collier counties.